Tag: Banking & Financial Regulation

  • Credit risk is linked to liquidity hoarding in African banks

    What the study found

    The study found that rising credit risk is associated with banks hoarding liquidity, meaning they shift assets toward liquid instruments and reduce off-balance-sheet exposures. It also found that stronger corruption control weakens this risk-averse response, while global uncertainty strengthens it.

    Why the authors say this matters

    The authors conclude that the findings have policy implications for credit risk management, institutional reform, and targeted small and medium-sized enterprise financing. They say these steps matter for supporting financial intermediation and sustainable economic growth in emerging and developing markets.

    What the researchers tested

    The researchers used a fixed-effects panel model on an unbalanced panel of 474 commercial banks across 47 African countries from 2013 to 2022. They also used a two-step system generalized method of moments (GMM) estimator to address possible endogeneity, plus bank-size subsamples and alternative proxies.

    What worked and what didn't

    The main pattern reported was that higher credit risk was linked to more liquidity hoarding. Stronger corruption control appeared to reduce that effect, while global uncertainty appeared to amplify it.

    What to keep in mind

    The abstract does not describe detailed limitations beyond noting the use of robustness checks. The findings are based on commercial banks in African countries over the 2013 to 2022 period.

    • Higher credit risk was associated with banks holding more liquid assets.
    • Banks also scaled back off-balance-sheet exposures when credit risk rose.
    • Stronger corruption control reduced the liquidity-hoarding response.
    • Global uncertainty increased the liquidity-hoarding response.
    • The study used data from 474 commercial banks in 47 African countries.
  • Bank diversification shows mixed effects on performance

    What the study found

    The review found that the effects of bank diversification on performance are heterogeneous and depend on context. The authors report that diversification in commercial banks can sometimes improve profitability and valuations, but in other settings it can increase earnings volatility and lower risk-adjusted performance.

    Why the authors say this matters

    The study suggests that bank managers can use these findings to align diversification strategies with changing economic conditions. The authors also conclude that policymakers may use the results to design regulations that adapt to macroeconomic fluctuations.

    What the researchers tested

    The researchers conducted a PRISMA 2020-based systematic literature review using Scopus data from 2006 to 2025. They also used bibliometric analysis with VOSviewer 1.6.20 and RStudio 4.4.3 to identify themes and citation patterns.

    What worked and what didn't

    The findings indicate that diversification can work in some contexts by improving profitability and valuations. However, the review also found cases where diversification was associated with higher earnings volatility and weaker risk-adjusted performance, and the impact of monetary policy was described as significant but mediated by broader macroeconomic factors.

    What to keep in mind

    The review covers commercial banks and is based on studies indexed in Scopus from 2006 to 2025. The abstract does not provide a single uniform effect, and it does not describe detailed study-level limitations beyond noting that results are context-dependent.

    • Diversification in commercial banks has mixed effects on performance.
    • The review found context-dependent links to profitability, valuations, earnings volatility, and risk-adjusted performance.
    • Monetary policy was identified as important, but its effects were mediated by broader macroeconomic conditions.
    • The study used a PRISMA 2020-based systematic review of Scopus literature from 2006 to 2025.
    • Bibliometric tools were used to map themes and citation patterns.
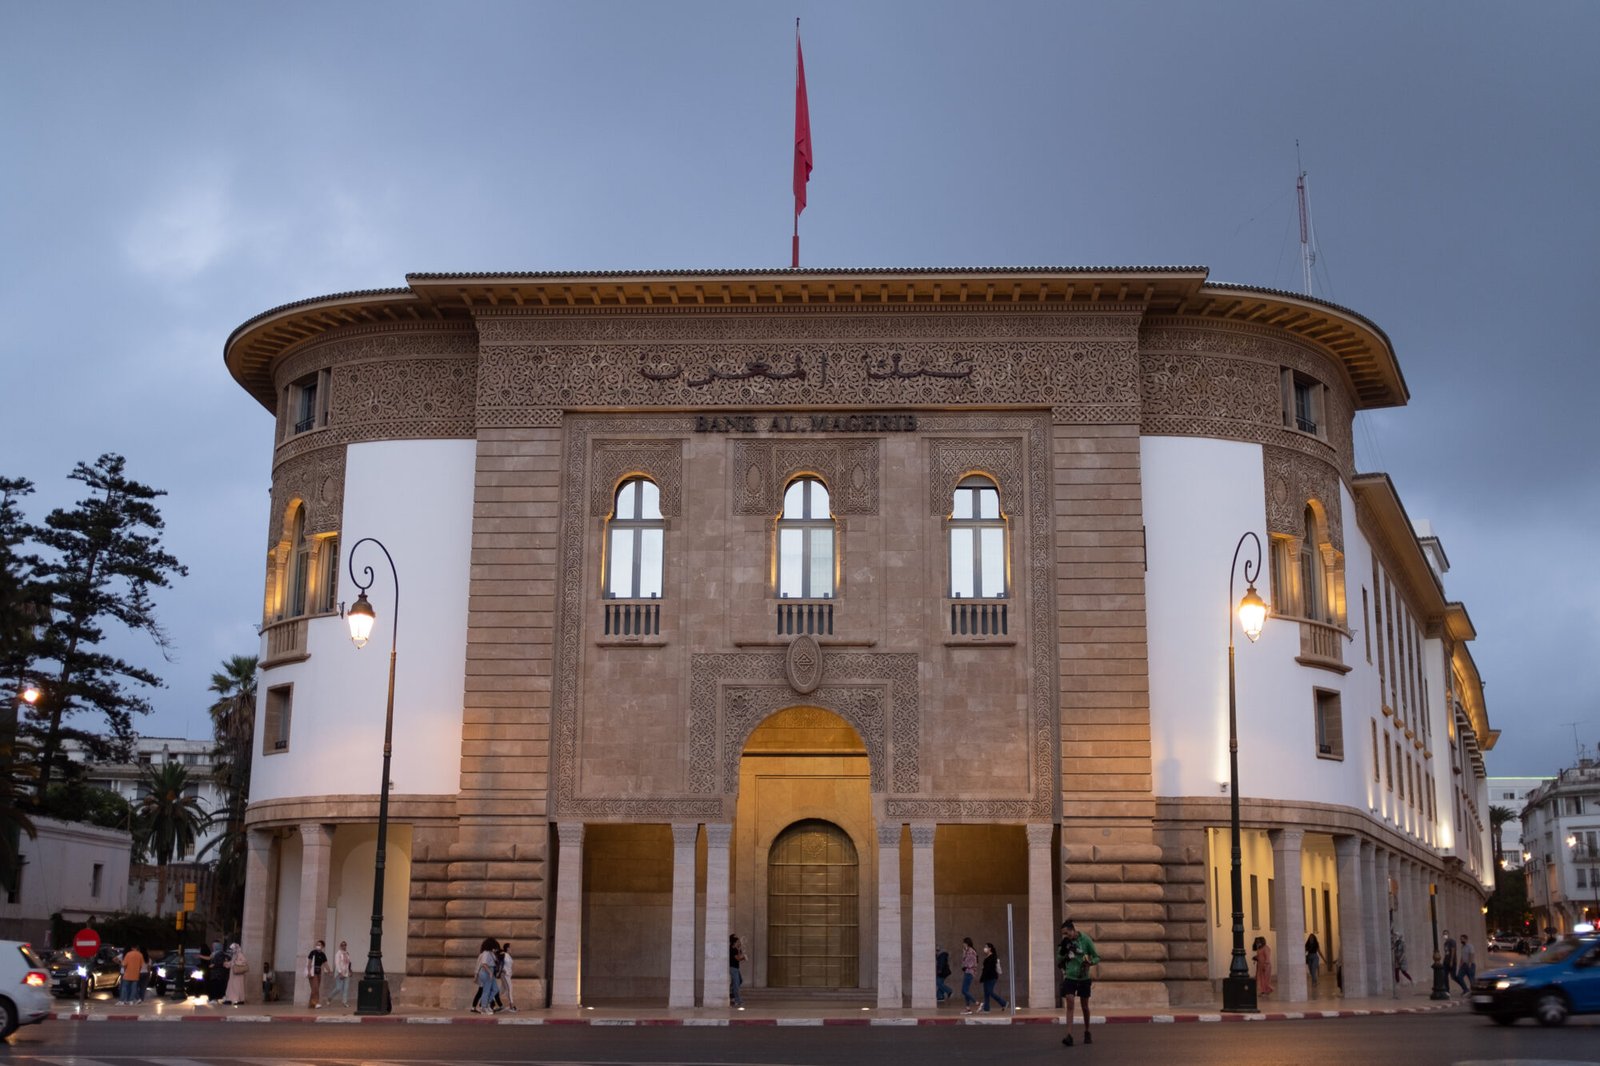
  • Policy rate changes did not significantly affect bank credit in Morocco

    Policy rate changes did not significantly affect bank credit in Morocco

    What the study found

    The study found that bank credit to Morocco's non-financial private sector showed strong short-run inertia, meaning it did not respond significantly to policy-rate changes over the short term. It also found a stable long-run relationship in credit, but no significant long-run elasticities for monetary policy or credit risk variables.

    Why the authors say this matters

    The authors conclude that monetary transmission in Morocco appears to work gradually and indirectly, mainly through prudential and balance-sheet channels rather than the conventional interest-rate channel. They suggest that the effectiveness of monetary policy depends on prevailing risk conditions and how those conditions interact with prudential frameworks in bank-based emerging financial systems.

    What the researchers tested

    The researchers analyzed monthly data from 2006 to 2023 for bank credit granted to the non-financial private sector in Morocco. They used an autoregressive distributed lag and error-correction model (ARDL-ECM), which separates short-run credit movements from long-run adjustment, and they accounted for possible structural breaks.

    What worked and what didn't

    Changes in the policy rate did not have a statistically significant short-run effect on bank credit. The bounds test supported a stable long-run equilibrium relationship in credit, but the study did not identify significant long-run effects from monetary policy or credit risk variables; instead, short-run adjustment mechanisms, especially credit risk and balance-sheet allocation, appeared to drive the dynamics.

    What to keep in mind

    The summary does not provide detailed limitations beyond the study's focus on Morocco and the 2006–2023 period. The results are specific to a bank-dominated emerging economy and to the variables and model used in the analysis.

    • Monthly data from Morocco covering 2006–2023 were analyzed.
    • The policy rate was not a statistically significant short-run driver of bank credit.
    • A stable long-run equilibrium relationship in credit was supported by the bounds test.
    • No significant long-run elasticities were found for monetary policy or credit risk variables.
    • Credit dynamics appeared to be driven mainly by short-run adjustment, credit risk, and balance-sheet allocation.
  • Asset shocks spill over differently in liquidity traps

    What the study found

    The study finds that shocks to asset supply or demand can have different international spillovers when an economy is in a liquidity trap, a situation where interest rates are near zero and monetary policy is constrained. In the model, a decrease in assets issued abroad creates an asset shortage at home.

    Why the authors say this matters

    The authors suggest that the supply of bonds matters in this non-Ricardian framework, where households value liquidity and asset scarcity affects outcomes. They conclude that the same shock can have different effects in normal times and in a liquidity trap.

    What the researchers tested

    The researchers built a two-country heterogeneous-agent non-Ricardian model with asset scarcity and financial frictions in international capital markets. They examined how shocks affecting the supply or demand of assets transmit across countries, especially when one economy is in a liquidity trap.

    What worked and what didn't

    In normal times, a decrease in the supply of assets issued abroad lowers the nominal interest rate and stimulates investment and output. In a liquidity trap, the same shock instead leads to deflation, an appreciation of the currency, and may cause a recession.

    What to keep in mind

    The summary provides results from a theoretical model, not from an empirical study. The abstract does not describe empirical data, specific calibration choices, or additional limitations.

    • The study models two countries with asset scarcity and financial frictions in international capital markets.
    • A demand for liquidity emerges because the framework is non-Ricardian, meaning the supply of bonds matters.
    • A fall in assets issued abroad creates an asset shortage at home.
    • In normal times, that shock lowers nominal interest rates and supports investment and output.
    • In a liquidity trap, the same shock leads to deflation, currency appreciation, and may cause a recession.
  • Fund holding networks heighten systemic risk in financial institutions

    What the study found

    The study found that fund holding networks among financial institutions significantly exacerbate systemic financial risk. The authors also report that governance convergence, synchronized share prices, and asset homogeneity are key mechanisms in this effect.

    Why the authors say this matters

    The authors conclude that the findings provide empirical support for reducing systemic financial risk by strengthening corporate governance within financial institutions, improving the quality of information disclosure, and enhancing supervision over fund shareholdings. They also suggest that limiting or reducing concentration in fund holdings may lessen the network's impact on systemic risk.

    What the researchers tested

    The researchers constructed a fund holding network among financial institutions using data from listed financial institutions from 2013 to 2024. They then empirically analyzed how this network is related to systemic financial risk and examined possible underlying mechanisms.

    What worked and what didn't

    Higher centrality in the fund holding network was associated with greater influence on systemic risk. The network appears to amplify systemic risk through governance convergence, stock price synchronicity, and homogenization of asset structure; stronger internal governance and better information disclosure were linked with mitigation of this risk.

    What to keep in mind

    The summary does not describe the study's limitations in detail. The findings are based on listed financial institutions in China over 2013 to 2024, so the scope is limited to that setting.

    • Fund holding networks among financial institutions were found to significantly exacerbate systemic financial risk.
    • Governance convergence, synchronized share prices, and asset homogeneity were identified as key mechanisms.
    • Financial institutions with higher network centrality had greater influence on systemic risk.
    • Better governance and information disclosure were linked with lower systemic financial risk.
    • High concentration of fund ownership was reported to aggravate risk.
  • Negative interest rates are linked to lower bank loan loss provisioning

    What the study found

    The study found that banks in countries adopting negative interest rate policy showed a contraction in loan loss provisioning. It also found that this negative interest rate policy effect depends on country- and bank-specific characteristics, including inflation, bank size, and bank specialisation.

    Why the authors say this matters

    The authors do not state a broader practical implication in the abstract beyond examining how negative interest rate policy relates to bank credit risk-taking. They present the findings as relevant for understanding how the policy interacts with bank and country conditions.

    What the researchers tested

    The researchers studied 1,958 banks across 29 OECD countries from 2011 to 2017. They used a triple difference method, and they also used a quadruple difference model and propensity score matching to check the robustness of the triple difference results.

    What worked and what didn't

    The triple difference analysis showed a contraction in loan loss provisioning in countries that adopted negative interest rate policy. The additional methods, quadruple difference and propensity score matching, were used to test robustness, but the abstract does not give separate detailed results for those checks.

    What to keep in mind

    The abstract does not provide detailed effect sizes or explanation of the mechanisms behind the findings. It also does not describe limitations beyond noting that the effect varies with inflation, bank size, and bank specialisation.

    • Banks in negative interest rate policy countries showed lower loan loss provisioning.
    • The effect varied with inflation, bank size, and bank specialisation.
    • The study covered 1,958 banks in 29 OECD countries from 2011 to 2017.
    • The authors used triple difference analysis and checked robustness with quadruple difference and propensity score matching.
  • Several bank and macroeconomic factors affect non-interest income

    What the study found

    The study found that different bank-specific and macroeconomic factors are linked to non-interest income at Vietnamese commercial banks. In particular, some factors were positively associated with non-interest income, while others were negatively associated with it, and a few were not statistically significant.

    Why the authors say this matters

    The authors conclude that the findings offer policy implications to improve banks’ operational efficiency. The study suggests that identifying which factors are associated with non-interest income may help guide bank management and policy for Vietnamese commercial banks.

    What the researchers tested

    The researchers reviewed theoretical and prior literature on non-interest income, which is income a bank earns from sources other than interest. They then built a framework and empirical model for Vietnam using an unbalanced panel dataset of 24 Vietnamese commercial banks from 2011 to 2023, estimated several panel regression models, selected a random-effects model after specification tests, and used Feasible Generalized Least Squares to address error variance issues.

    What worked and what didn't

    Bank size, deposit-to-asset ratio, credit risk provision ratio, income diversification, inflation, and the COVID-19 pandemic showed positive effects on non-interest income. Loan-to-asset ratio and state ownership showed negative effects, while equity ratio and real GDP growth were not statistically significant.

    What to keep in mind

    The abstract does not describe detailed limitations beyond the study being focused on 24 Vietnamese commercial banks and the 2011 to 2023 period. The summary also does not specify how the measured associations should be interpreted beyond the reported model results.

    • The study examined non-interest income in 24 Vietnamese commercial banks from 2011 to 2023.
    • Bank size, deposit-to-asset ratio, credit risk provision ratio, income diversification, inflation, and COVID-19 were positively associated with non-interest income.
    • Loan-to-asset ratio and state ownership were negatively associated with non-interest income.
    • Equity ratio and real GDP growth were not statistically significant.
    • The authors say the findings have policy implications for improving operational efficiency.
  • Bank holding companies favored stronger affiliates during crisis

    What the study found

    The study found that parent firms did not reliably support distressed subsidiaries during the 2007–2009 financial crisis. Instead, bank holding companies (BHCs) favored stronger, more liquid, and more resilient affiliates when allocating internal capital.

    Why the authors say this matters

    The authors conclude that regulatory assumptions about automatic parent support do not match actual behavior. They suggest that monitoring sibling fragility across conglomerates, nonbank affiliates, and intra-group capital flows may be needed to improve financial stability.

    What the researchers tested

    The researchers examined the 2007–2009 financial crisis using novel measures of sibling distress and detailed parent-affiliate funding flows within BHCs. They assessed how capital moved across affiliates and how that pattern changed under stress.

    What worked and what didn't

    Capital allocation within BHCs disproportionately favored stronger affiliates. The results indicate that profitable parents became more selective under stress, while nonbank subsidiaries acted as important internal liquidity providers when external markets froze. Support for weaker affiliates was limited.

    What to keep in mind

    The abstract does not describe specific limitations beyond the study's focus on the 2007–2009 crisis and bank holding companies. The findings are presented as evidence about internal capital markets during that period, not as a broader test of all firms or crises.

    • Parent support for distressed subsidiaries was selective, not reliable, during the 2007–2009 crisis.
    • Bank holding companies allocated more capital to stronger, more liquid, and more resilient affiliates.
    • Profitable parents became more selective under stress.
    • Nonbank subsidiaries provided internal liquidity when external markets froze.
    • The authors say supervisory frameworks should monitor sibling fragility and intra-group capital flows.
  • Fiscal contraction is linked to lower NPLs in the long run

    What the study found

    The study found that fiscal contraction, meaning an improvement in the primary balance from deficit toward surplus, is associated with lower non-performing loans (NPLs) in the long run. It also found a short-run increase in NPLs after fiscal contraction.

    Why the authors say this matters

    The authors say this matters because the study addresses a fiscal policy–NPL connection that is often overlooked in banking stability literature. They conclude that the findings extend industrial organization theory of banking to this relationship in a developing, resource-rich economy.

    What the researchers tested

    The researchers proposed a generalized theoretical framework that augments industrial organization theory of banking with liquidity preference theory. They tested it using bank-level quarterly data from Guyana from 2009: Q4 to 2024: Q4 and a Panel Autoregressive Distributed Lag Pooled Mean Group (ARDL-PMG) model, which is a panel time-series method.

    What worked and what didn't

    A one-percentage-point improvement in the seasonally adjusted primary balance as a share of gross domestic product was associated with a 0.473 percentage point decrease in NPLs in the long run. In the short run, fiscal contraction had a coefficient of 0.103, indicating a temporary increase in NPLs, likely because of pressure on borrowers' debt-service capacity. Higher oil prices and bank efficiency were reported to significantly lower NPLs, while GDP growth, inflation, the real effective exchange rate, and the COVID-19 pandemic were statistically insignificant in this framework.

    What to keep in mind

    The abstract does not describe the study's limitations in detail. The findings are based on bank-level quarterly data from Guyana and may reflect that specific setting and period.

    • Fiscal contraction was associated with lower NPLs in the long run.
    • A one-percentage-point improvement in the primary balance was linked to a 0.473 percentage point long-run decrease in NPLs.
    • Fiscal contraction was linked to a temporary short-run increase in NPLs, with a coefficient of 0.103.
    • Higher oil prices and bank efficiency significantly lowered NPLs in the model.
    • GDP growth, inflation, the real effective exchange rate, and COVID-19 were statistically insignificant.
  • Public lending contracts can better align bank incentives

    What the study found

    The authors propose changes to public lending design that aim to improve incentive alignment in crisis lending. They argue that subsidized public lending can create risks for both banks and firm borrowers, and that contract design can help address these risks.

    Why the authors say this matters

    The study suggests that better-designed public lending contracts may help public lenders respond more effectively in an economic crisis. The authors conclude that aligning incentives between public lenders, commercial banks, and firms is important for reducing problems in subsidized lending schemes.

    What the researchers tested

    The paper combines casual empirical observations, institutional analysis, and normative theoretical modeling. It uses the emergency lending scheme offered by Germany’s national development bank, KfW, during the COVID-19 crisis as a case study of two-tier lending relationships involving the development bank, participating commercial banks, and firm borrowers.

    What worked and what didn't

    Based on the case study, the authors identify obstacles to efficient contracting in these public lending relationships. They propose a set of contracts that would make banks less likely to seek public support for financially strong firms and for non-viable zombie firms, while allowing firms needing support to choose contracts that reveal their rating and receive funds based on crisis-induced needs.

    What to keep in mind

    The summary provided describes proposals and case-based evidence, not a tested policy intervention. The abstract does not give outcome data for the proposed contracts, and it does not describe limitations beyond the scope of the case study.

    • The paper proposes ways to improve public lending design during an economic crisis.
    • It examines Germany’s KfW emergency lending scheme during the COVID-19 crisis.
    • The authors identify incentive risks in two-tier lending relationships among public lenders, commercial banks, and firms.
    • They propose contracts meant to discourage support for financially strong firms and non-viable zombie firms.
    • They suggest banks should retain part of borrower default risk to improve incentive alignment.